Here’s some good news you probably didn’t hear on the evening news: starting January 1, 2027, Missouri will let people who file bankruptcy keep a lot more of their property.
In 2026, the Missouri legislature passed a law raising most of the state’s bankruptcy exemptions. Exemptions are the rules that decide how much of your property is protected from creditors when you file. If that’s new to you, start with my guide to Missouri bankruptcy exemptions.
What’s Changing
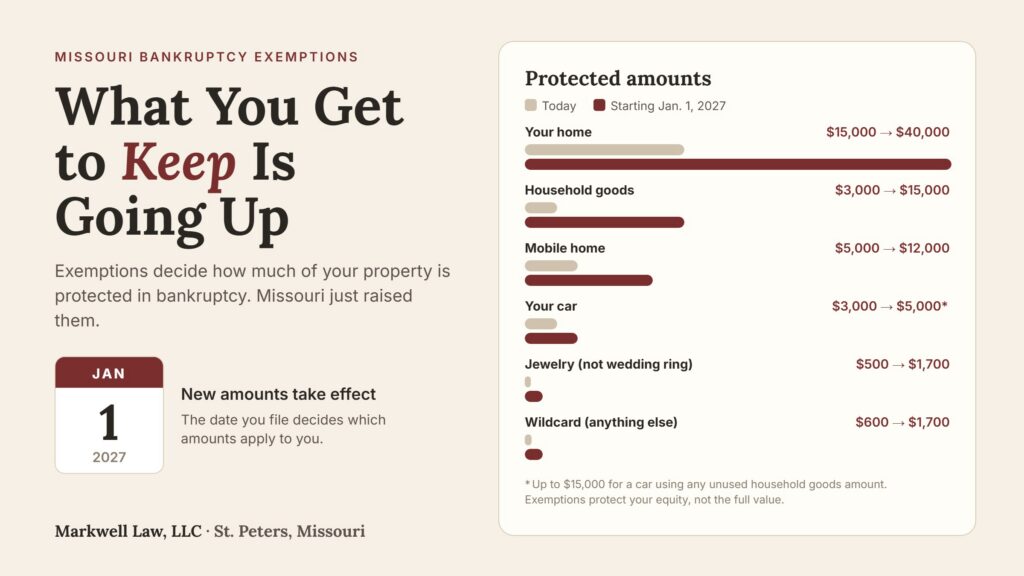
- Your home (homestead): $15,000 goes to $40,000
- Household goods and furniture: $3,000 goes to $15,000
- Your car: $3,000 goes to $5,000, and up to $15,000 if you use any unused household goods exemption
- Mobile home: $5,000 goes to $12,000
- Jewelry (other than your wedding ring): $500 goes to $1,700
- “Wildcard” (anything else): $600 goes to $1,700
The homestead jump is the big one. It has been stuck at $15,000 since 2003, while home values around St. Charles County and St. Louis kept climbing. The new law also adjusts the amounts for inflation every three years starting in 2029, so we shouldn’t have to wait another twenty-plus years for the next update.
Why the Date You File Matters
Your exemptions are locked in on the day your case is filed. File on December 31, 2026, and you get the old amounts. File on January 4, 2027, and you get the new ones.
For most of my clients, it won’t make a difference, because everything they own already fits under the current exemptions. But if you have real equity in your home or your car, waiting a few weeks could protect thousands of dollars.
Should You Wait?
Not necessarily. If your wages are being garnished, a creditor is about to empty your bank account, or you’re facing a foreclosure sale, waiting can cost you more than it saves. The right answer depends on what you own, what you owe, and what your creditors are doing right now.
Not sure whether to file now or after January 1? Contact Markwell Law, LLC in St. Peters, and we’ll look at your situation together. For the full rundown on what’s protected, including jointly owned property, see Missouri Bankruptcy Exemptions: What You Get to Keep.